How Can University Endowments Recover Withholding Tax Lost On Cross-Border Dividends?
University endowments can recover excess dividend withholding tax (WHT) where the legal recipient qualifies for treaty relief or a source-country exemption. Switzerland, for example, deducts 35% from Swiss company dividends, with eligible foreign investors claiming treaty refunds through the Swiss Federal Tax Administration (SFTA). Recovery depends on the claimant’s residence, status, beneficial ownership and payment […]
How Have Insurers Recovered or Challenged Dividend Withholding Tax Across Markets?
Insurance companies investing in foreign equities can lose dividend income to withholding tax (WHT), even where treaty relief or legal protections support a lower tax burden. Switzerland, for example, generally levies 35% on dividends, with eligible investors seeking treaty-based refunds through the Swiss Federal Tax Administration. This insurer WHT case study comparison examines a Luxembourg […]
How Can Insurance Companies Establish Treaty Eligibility To Reclaim Dividend Withholding Tax?
Insurance companies can reclaim excess dividend withholding tax (WHT) by establishing treaty residence, beneficial ownership and compliance with applicable anti-abuse rules. For example, the United States generally deducts 30% from US-source dividends paid to foreign corporations. An eligible UK-resident insurer receiving ordinary portfolio dividends may qualify for 15% under the UK–US treaty and seek repayment […]
How Can Insurance Companies Identify and Recover Overpaid Dividend WHT on Cross-Border Investments?
Insurance companies can recover foreign dividend withholding tax (WHT) where deductions exceed the amount permitted under an applicable tax treaty, domestic exemption or other legal provision. Statutory rates include 30% in the United States, 20% for identified foreign corporate recipients in Finland and 15% in the Netherlands. The Internal Revenue Service (IRS), Finnish Tax Administration […]
Case Study: How Can a Sovereign Fund Recover Historic Dividend Withholding Tax?
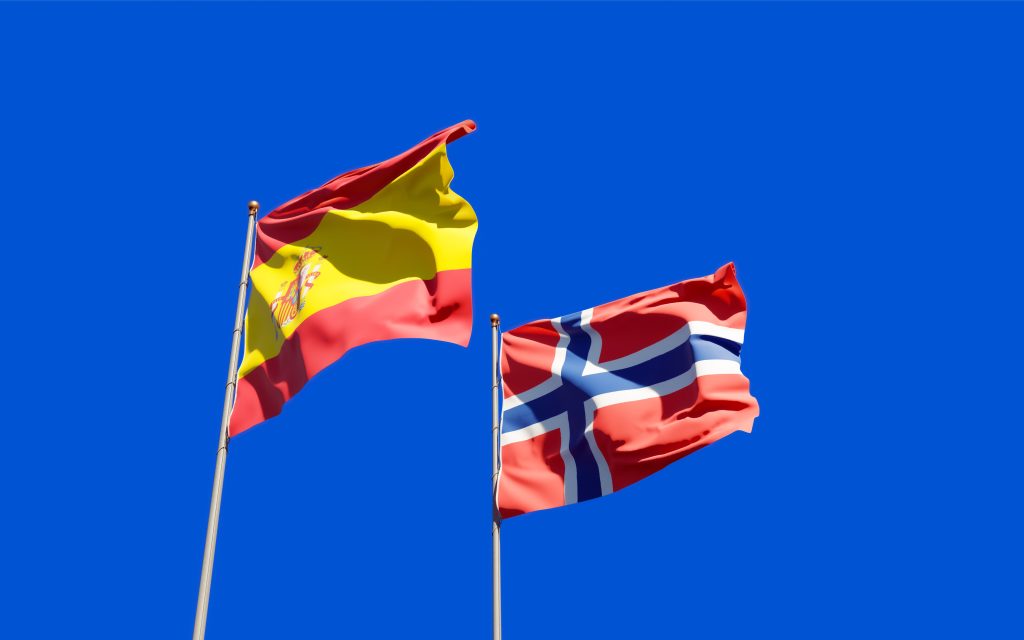
A sovereign fund can recover historic dividend withholding tax (WHT) when deductions exceed its legal tax liability. In February 2021, Spain’s Supreme Court upheld Norway’s Government Pension Fund Global’s right to reclaim Spanish dividend WHT of 15%–18%. The Spanish Tax Agency (AEAT) had imposed WHT despite comparable domestic public institutions benefiting from exemptions. The recovery […]
How Does Government Pension Fund Status Differ from Sovereign Fund Status When Claiming Dividend WHT Exemptions and Refunds?
Government pension funds and sovereign wealth funds may qualify for different dividend withholding tax (WHT) exemptions, even when both are publicly owned. In the United States, the standard dividend WHT rate is 30%, while qualifying sovereign investors may receive a 0% exemption under Section 892 of the Internal Revenue Code. Government pension funds may instead […]
How can sovereign investors use sovereign immunity to recover dividend tax worldwide?
Sovereign investors can recover dividend withholding tax (WHT) where the source country recognises sovereign immunity, a statutory exemption or an applicable treaty entitlement. In the United States, the standard 30% withholding rate can fall to 0% for qualifying investment income under section 892, administered by the Internal Revenue Service (IRS). Relief requires evidence of eligibility; […]
What do sovereign wealth funds need to know about dividend WHT recovery?
The financial effect extends beyond an individual dividend. Repeated deductions across large equity portfolios can leave substantial amounts awaiting review, documentation or repayment. A fund should therefore assess withholding tax alongside investment income reconciliation, rather than assume that the net dividend reflects its final entitlement. Recovery also differs from investment selection. A fund can hold […]
How do investors reclaim Austrian dividend WHT through the mandatory electronic refund procedure?
Austria generally deducts 27.5% withholding tax (WHT) from dividends, and eligible non-resident investors can reclaim excess tax through the Finanzamt für Großbetriebe. The recovery route requires an electronic advance notification followed by a signed, residence-certified paper application sent by post. For dividends from shares, the current form is ZS-RD-DIAG, rather than the legacy ZS-RE1 or […]
How Can Foreign Investors Recover Austria’s 27.5% Dividend WHT?
Austria generally deducts 27.5% dividend withholding tax (WHT), but eligible foreign investors can reclaim tax above their treaty rate or applicable exemption. Austria’s Finanzamt für Großbetriebe handles these refund claims through the prescribed electronic pre-notification and signed, residence-certified postal application. For dividends from shares, the relevant form is ZS-RD-DIAG. Austria dividend WHT recovery depends on […]