Our Expert Blogs
Endowments and foundations can recover excess dividend withholding tax (WHT) through treaty claims, domestic exemptions or challenges to discriminatory taxation. The United States generally applies 30% to US-source dividends paid to foreign persons, subject to treaty reductions and statutory exemptions. The Internal Revenue Service (IRS) administers these rules; recovery may involve a withholding-agent correction or […]
Insurance companies investing in foreign equities can lose dividend income to withholding tax (WHT), even where treaty relief or legal protections support a lower tax burden. Switzerland, for example, generally levies 35% on dividends, with eligible investors seeking treaty-based refunds through the Swiss Federal Tax Administration. This insurer WHT case study comparison examines a Luxembourg […]
Dividend withholding tax affects the Solvency II capital calculation through asset valuation, own funds and the risk treatment of recoverable amounts. There is no single Solvency II withholding tax rate: Germany, for example, deducts 26.375%, comprising 25% capital income tax plus a solidarity surcharge of 5.5% of that tax. A qualifying UK-resident beneficial owner of […]
Insurance companies can reclaim excess dividend withholding tax (WHT) by establishing treaty residence, beneficial ownership and compliance with applicable anti-abuse rules. For example, the United States generally deducts 30% from US-source dividends paid to foreign corporations. An eligible UK-resident insurer receiving ordinary portfolio dividends may qualify for 15% under the UK–US treaty and seek repayment […]
Unit-linked and general account assets can qualify for dividend withholding tax (WHT) recovery, but entitlement depends on legal ownership, beneficial ownership and the applicable tax treaty. For example, Switzerland generally deducts 35% WHT from dividends, while the Swiss Federal Tax Administration (FTA) administers treaty-based refund claims. Insurers may recover excess deductions through relief at source […]
Insurance companies can recover foreign dividend withholding tax (WHT) where deductions exceed the amount permitted under an applicable tax treaty, domestic exemption or other legal provision. Statutory rates include 30% in the United States, 20% for identified foreign corporate recipients in Finland and 15% in the Netherlands. The Internal Revenue Service (IRS), Finnish Tax Administration […]
Insurance companies can recover excess dividend withholding tax (WHT) where an applicable tax treaty, domestic exemption or other legal provision establishes a repayment entitlement. Standard dividend WHT rates include 30% in the United States, 26.375% in Germany, 20% for identified foreign corporate recipients in Finland and 15% in the Netherlands. The Internal Revenue Service (IRS), […]
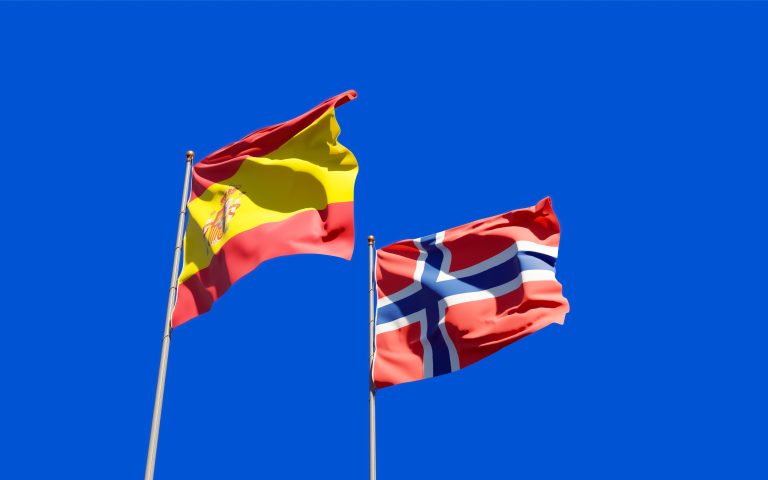
A sovereign fund can recover historic dividend withholding tax (WHT) when deductions exceed its legal tax liability. In February 2021, Spain’s Supreme Court upheld Norway’s Government Pension Fund Global’s right to reclaim Spanish dividend WHT of 15%–18%. The Spanish Tax Agency (AEAT) had imposed WHT despite comparable domestic public institutions benefiting from exemptions. The recovery […]
Government pension funds and sovereign wealth funds may qualify for different dividend withholding tax (WHT) exemptions, even when both are publicly owned. In the United States, the standard dividend WHT rate is 30%, while qualifying sovereign investors may receive a 0% exemption under Section 892 of the Internal Revenue Code. Government pension funds may instead […]
Sovereign wealth funds (SWFs) must provide evidence of government status, tax residence, beneficial ownership and investment eligibility to claim dividend withholding tax (WHT) exemptions or treaty relief. Standard dividend WHT rates include 30% in the United States and 25% in Canada, although qualifying sovereign investors may receive a 0% exemption. The Internal Revenue Service (IRS), […]